Published 26 Sep 2026 · Last reviewed 26 Sep 2026 · 2 min read
In short: Age is only a starting point. Goal horizon, job stability, liabilities, dependants, pension assets and ability to withstand loss matter more than a “100 minus age” rule.
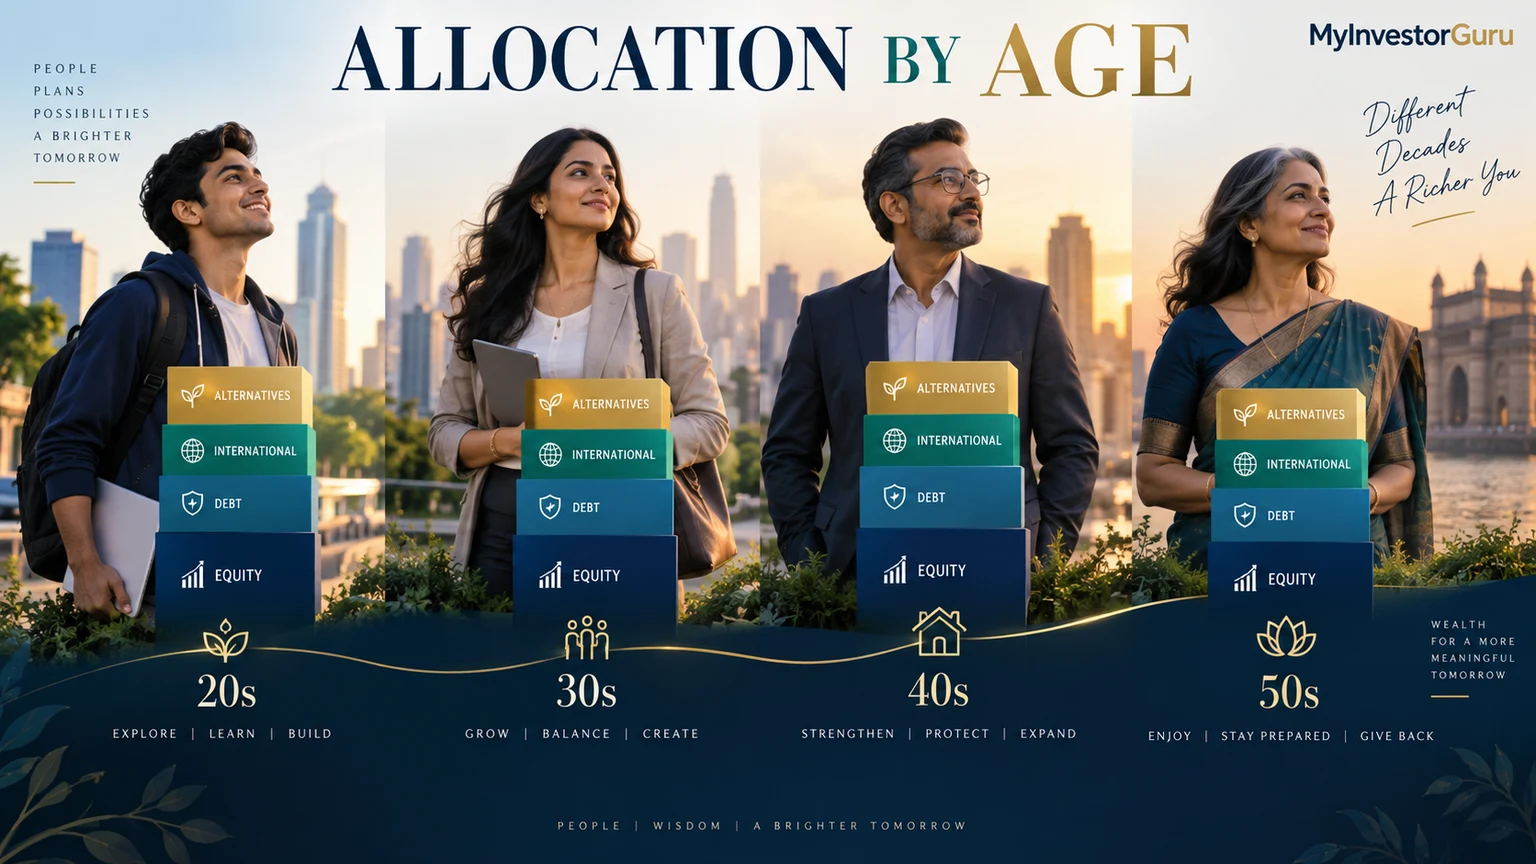
In your 20s
Long horizons may support higher equity, but first build emergency savings, insurance and basic diversification. Do not confuse youth with unlimited risk capacity.
In your 30s
Home, children and career changes can create competing goals. Use separate goal buckets and avoid counting a self-occupied home as liquid retirement capital.
In your 40s
Measure goal funding, raise contributions and reduce concentration in employer stock or one property. Start moving near-term goal money away from volatile assets.
In your 50s
Sequence-of-returns and liquidity risk become central. Create a retirement cash-flow plan while retaining enough growth assets for longevity and inflation.
Use ranges, not dogma
Document target ranges for equity, debt, gold and cash; rebalance annually or when bands are breached. Tax and exit costs matter.
Action checklist
- Write down the goal, amount and deadline.
- Check liquidity, risk, costs, tax and exit restrictions.
- Use only regulated intermediaries and original documents.
- Record assumptions and review after major life or rule changes.
Sources and methodology
We prioritised official Indian regulator, tax authority and industry-body material. Numerical examples are illustrations, not forecasts. Product rates, limits and taxation should be rechecked on the transaction date.
- SEBI Investor — Introduction to Mutual Funds (accessed 2026-09-26)
Frequently asked questions
Is this article investment advice?
No. It is general education. Your goals, taxes, cash flow and risk capacity require individual assessment.
Can returns be guaranteed?
No. Market-linked investments can lose value; past performance does not guarantee future results.
What is the quick answer on Allocation by Age?
Age is only a starting point. Goal horizon, job stability, liabilities, dependants, pension assets and ability to withstand loss matter more than a “100 minus age” rule.
asset allocation by age India
Last reviewed: September 2026 · Educational only — not investment, tax, legal or property advice. See Disclaimer.